Premiums 2027 · official FOPH data
Calculate your 2027 health insurance premium and save
All basic insurance offers in your premium region compared, with each insurer’s premium history since 2016. You can then request a quote in a minute.
- +5.0 %average premium increase 2027 according to the FOPH
- 30.11.your cancellation must reach the insurer by then
- 32 insurersall premium regions in Switzerland
The premium data could not be loaded. Please reload the page.
Results 2027
Example calculation for 8001 Zürich, born 1985, employed. Change the details above to see your premiums.
- Standard: free choice of doctor, you go directly to any doctor or specialist.
- Family doctor: always go to your chosen family practice first (with some insurers only from a list). It refers you to specialists.
- HMO: you are tied to a specific health centre. Treatment and referrals go through this centre.
- Telmed: before every doctor’s visit, call the telemedicine centre or check via the insurer’s app first.
Your insurer does not offer this model in your region. Please check the model on your policy.
Found a cheaper insurer?
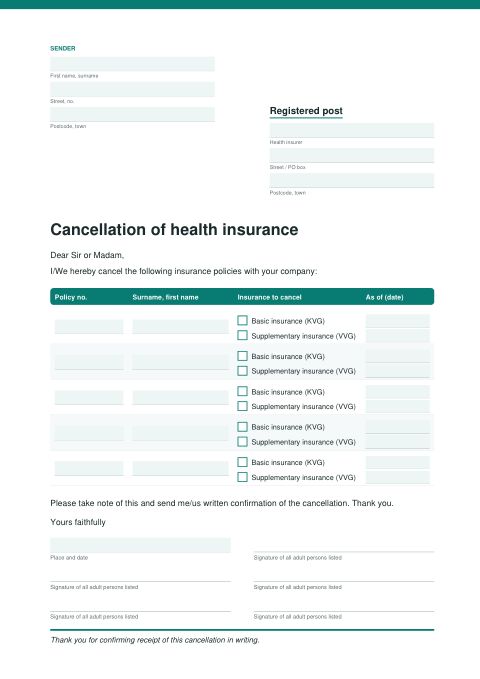
Download the cancellation form for your current insurer right here (PDF). For basic and supplementary insurance, up to 5 people, can be filled in on the computer. The cancellation must reach your insurer by 30 November at the latest.
Download cancellation form (PDF)No gap in cover when you switch: for basic insurance, your current insurance only ends once the new insurer has confirmed that you are insured without interruption (Art. 7 para. 5 KVG). Until then, you remain insured with your old insurer.
Premium history
Annual figures as a table
Source: FOPH, dataset “Health insurance premiums” on opendata.swiss, as at 29.9.2026. For each insurer and model, the cheapest approved rate, rounded to 10 centimes. Discounts for the third and further children are not taken into account. The insurer’s quote is binding.
Supplementary insurance
Supplementary insurance benefits
Basic insurance does not pay for many things. See how much each insurer contributes towards complementary medicine, fitness, massages, glasses, travel and teeth, and request your personal offer.
Quote and advice
Request a quote in three short steps
We obtain the binding quote from the insurer, check it with you and help you switch. Free of charge and without obligation for you.
- Your selection is already includedWe take the insurer, model, deductible and place of residence straight from the calculator.
- Personal, not a call centreYou decide whether we e-mail or call you, and when.
- In good time before 30 NovemberOn request, you will receive a cancellation template for your current insurer.
Advice from FINMA-registered intermediaries Our advisers meet the requirements of the revised Insurance Supervision Act (ISA) and are listed in FINMA’s register of insurance intermediaries (F01044050, F01495797). Legal notice
Prefer to talk directly? 043 200 02 92 or info@neutrale-versicherungsberatung.com
- Request
- Contact
- Confirm
Questions and answers
Cancellation, models, deductible
By when can I cancel my basic insurance?
Your cancellation must reach your health insurer by 30 November at the latest; you then switch on 1 January. Send it by registered post and in good time. Your existing insurance only ends once the new insurer has confirmed that you are insured without a gap. With the ordinary deductible of CHF 300 in the standard model, you can also switch at the end of June, with cancellation by the end of March.
You can use our form for the cancellation. It applies to basic (KVG) and supplementary insurance (VVG) and for up to five people. You can fill it in directly on your computer or print it out and fill it in by hand. Then sign it and send it by registered post.
- Download the form and fill it in on your computer or by hand.
- Sign it: every adult signs personally, parents sign for their children.
- Send it by registered post so that it reaches your current insurer by 30 November at the latest.
Download cancellation form (PDF)
No gap in cover when you switch: for basic insurance, your current insurance only ends once the new insurer has confirmed that you are insured without interruption (Art. 7 para. 5 KVG). Until then, you remain insured with your old insurer.
Want to stay with your insurer and only change your model or deductible? For that, use our sample letters to your health insurer.
Is your advice independent and verified?
Yes. Our advisers are listed as insurance intermediaries in FINMA’s public register of intermediaries (Alessio Sarubbi F01044050, Roman Krasniqi F01495797) and meet the requirements of the revised Insurance Supervision Act (ISA/VAG), including those on training and continuing education. You can check these entries yourself in FINMA’s register. We compare offers from different health insurers; the premiums in the calculator come from the official FOPH data. Our advice is free of charge and non-binding for you.
How to recognise trustworthy advice is explained in our guide; all company details are in the legal notice.
When should I insure my baby?
Ideally before birth, preferably in the 5th to 7th month of pregnancy. Health insurers will then also accept your child into supplementary insurance without a health check. You only pay premiums from the month of birth. For basic insurance, you have three months after the birth, and it then applies retroactively.
Are the benefits the same with all health insurers?
Yes. Basic insurance benefits are set by law and are identical with all insurers. The differences are in premium, model and service. Every insurer must accept you for basic insurance without health questions.
Do I need accident cover?
If you work at least 8 hours a week for the same employer, you are insured against accidents through your employer and can exclude accident cover from your health insurance. For children, the self-employed, people not in work and pensioners, it remains included. What else changes when you retire is explained in our retirement guide.
What do family doctor, HMO and Telmed mean?
With these models, you first go to your family doctor or an HMO health centre, or call a telemedicine service. In return, the premium is usually lower than in the standard model with free choice of doctor. Emergencies are always exempt. Before switching, check whether your family doctor is on the insurer's list or whether the insurer has an HMO health centre near you, and which rules apply, for example whether you have to call before every visit to the doctor or use an app. If you do not follow the rules, you risk benefit cuts.
Which deductible is right?
With the highest deductible of CHF 2'500 you pay the lowest premium, but bear more of the costs yourself. On top of this there is a retention of 10 % of the costs, at most CHF 700 per year (children CHF 350). Whether the high deductible pays off depends on your expected costs. For adults, the threshold is around CHF 2'000 of doctor, hospital and medication costs per year: below that, the CHF 2'500 deductible usually works out cheaper; above it, the CHF 300 deductible. The reason: for the CHF 2'500 deductible, insurers may reduce the premium by no more than CHF 1'540 a year (70% of the additional risk of CHF 2'200). If your insurer gives a smaller discount, the threshold is lower. The deductible calculator works it out with your own figures, and we are also happy to do so during our advice.
I am moving to Switzerland or am a cross-border commuter. What applies?
If you move to Switzerland, you must take out basic insurance within three months of taking up residence; it then applies retroactively from the date of arrival. Cross-border commuters from Germany, France, Italy and Austria can choose within three months of starting work whether to insure themselves in Switzerland or in their country of residence.
Guide: moving to Switzerland, expats & cross-border commuters
Do I need supplementary hospital insurance?
No, it is voluntary. Basic insurance pays for the general ward of a listed hospital, but outside your canton of residence only up to the rate of your canton of residence. With supplementary hospital insurance, you can choose your hospital freely anywhere in Switzerland, and with semi-private or private also your room and doctor.
Where do the premiums come from?
From the premiums approved by the Federal Office of Public Health (FOPH), published in the dataset “Health insurance premiums” on opendata.swiss (as at 29.9.2026). For each insurer and model, the cheapest rate is shown, rounded to 10 centimes. The insurer’s quote is binding.